




Understanding Bridging Finance: When Speed Matters
Bridging finance is a short-term funding solution designed to help property buyers and investors move quickly when traditional mortgage finance is unavailable or cannot be arranged within the required timescale.
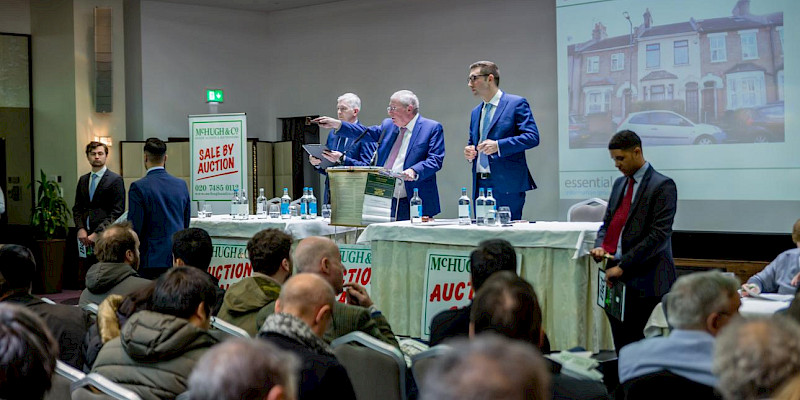
It can be particularly useful when purchasing at auction, buying a property that requires refurbishment, dealing with a chain break, or securing an investment opportunity where timing is critical.
What is bridging finance?
A bridging loan is a short-term secured loan, usually backed by property. Unlike a conventional mortgage, it is designed to provide funding for a relatively short period while a longer-term solution is arranged.
The most important question when considering bridging finance is: How will the loan be repaid?
This is known as the exit strategy and should be established before taking out the loan.
When can bridging finance be useful?
Bridging finance can be considered for:
-
Property purchases with tight completion deadlines
-
Auction purchases
-
Properties requiring significant refurbishment
-
Buying before an existing property has sold
-
Property investment and development projects
-
Commercial property transactions
-
Properties that are temporarily unsuitable for conventional mortgage finance
The ability to complete quickly can sometimes make the difference between securing an opportunity and losing it.
What does bridging finance cost?
Bridging finance is generally more expensive than a standard mortgage because it is designed for short-term and often more complex transactions.
Costs can include interest, arrangement fees, valuation fees and legal costs. Some lenders may allow interest to be retained or rolled up rather than paid monthly. This can assist with cash flow but increases the amount owed.
For this reason, it is important to consider the overall cost of the finance, rather than simply comparing headline interest rates.
The importance of the exit strategy
A credible exit strategy is fundamental to any bridging application.
Common exits include selling the property and repaying the loan from the proceeds, refinancing onto a conventional mortgage once the property is suitable for longer-term lending, or refinancing onto development or commercial finance.
The proposed exit should be realistic and supported by the property, the borrower's circumstances and the anticipated timescale.
Finding the right bridging solution
Bridging finance is not a one-size-fits-all product. Different lenders have different criteria, rates, fees, loan-to-value requirements and approaches to particular types of property and exit strategies.
As an independent mortgage adviser, I am not tied to a single lender or banking group. This allows me to consider a range of available lending options and identify a solution that is suitable for the client's individual circumstances and objectives.
Rather than focusing solely on the lowest headline rate, I consider the overall cost, lender criteria, flexibility and suitability of the facility. Where appropriate, this can help identify competitively priced finance from the available market.
Is bridging finance right for you?
Bridging finance can provide valuable flexibility when speed is important, but it is not automatically the cheapest or most suitable option.
The right solution depends on the property, amount required, financial circumstances, timescale and, most importantly, the proposed exit strategy.
If you are considering bridging finance for a purchase, refurbishment, investment or development project, professional advice can help you assess the available options and whether the proposed finance and exit strategy are appropriate for your circumstances.
About the Adviser
Hassan Khansa is a Mortgage & Protection Adviser and Mortgage Intermediary representing Echo Finance Limited, an FCA-authorised and regulated firm.
Hassan also has personal experience of property investment and development, providing practical insight into the challenges investors can face when timing, funding and exit strategies are critical.
He is also a member of the National Association of Commercial Finance Brokers (NACFB), the UK's largest trade association for commercial finance brokers, which promotes professional standards and good practice across the commercial finance sector.
Belgravia Finance is a trading style of Belgravia CG Limited. Mortgage and protection advice is subject to status, lender criteria and suitability. Your property may be repossessed if you do not keep up repayments on your mortgage.
Important: This article is for general information only and does not constitute personal financial advice. All mortgage and bridging finance applications are subject to lender criteria, affordability and individual circumstances.